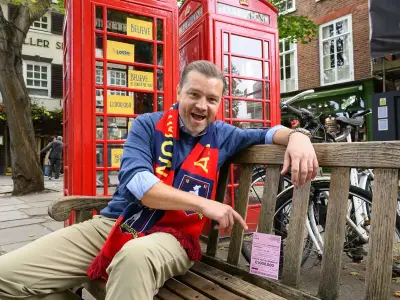
Jaqs Nelson, a 27-year-old principal manager consultant from Bromley, South East London, earns £130,000 a year but says he feels "broke" in London, with only £10,000 in savings despite his hefty salary. He takes home around £7,000 a month, more than triple the UK's average full-time wage, but burns through £6,000 of it on fixed costs and discretionary spending.
Monthly spending breakdown
Jaqs spends £3,000 on his mortgage and bills for a three-bedroom property, with leftover cash typically going to Uber rides and Deliveroo orders. His monthly outgoings include a £120 gym membership, £250 on takeaways, £150-£300 on date nights, and £1,500 on extras like holidays and travel. This leaves him with just £1,000-£1,500 for savings and investments on a good month.
He said: "I think even though you can have a high income, living in London is quite expensive. I got paid today but yesterday I was looking at my expenses and just on my fixed expenses, it was £3,000 for my mortgage, bills, Wi-Fi and everything."
Financial challenges and setbacks
Jaqs's earnings vary considerably due to commission and bonuses, making it hard to plan for the future. He lost £70,000 investing in an Amazon FBA venture selling baby mattresses, which failed to deliver returns. He also saw his rent jump from £800 to £1,950 monthly when he started renting solo in June 2024 after a relationship ended.
He said: "I was with a partner but we broke up, but my rent went from £800 we were splitting to £1,950. That was a lot to be forking out."
He now owns a property, but the purchase cost him £40,000 in stamp duty, legal fees, and renovation expenses. He used Yorkshire Building Society's £5,000 deposit scheme, available exclusively to first-time buyers purchasing properties valued at no more than £500,000, excluding new builds and flats. Jaqs funded the £5,000 deposit himself.
Savings goals and investment strategy
Jaqs considers himself a HENRY (High Earner Not Rich Yet) given his modest savings, which he reckons would only sustain three months of expenses if he lost his job. He is targeting £100,000 in savings within two years by depositing £3,000 monthly into his stocks and shares ISA and premium bonds.
Since March, he has been putting aside between £1,000 and £1,500 into investments, hoping to increase this to £3,000 with additional commission. He said: "All my savings every month go into investments with stocks and shares ISA until that's maxed out. I'll likely just save that once it's maxed, but I am also looking into premium bonds seeing as premium bond winnings are tax free."
He added: "I think people temporarily save so they have a buffer. I have split the money into a buffer and the long term, but I think most people's savings are going to be a mixture of what they are going to be needing right now. I'm at £14,000 right now but hope to reach £28,000 by the end of the year."
Lifestyle and future plans
Jaqs spends heavily on experiences with his partner, including meals out and holidays. A Deliveroo order can run to £30 for jerk chicken, while an Indian takeaway costs £50, and a Nando's adds up to around £40. Date nights range from £50 at the cinema to £130 at Everyman, with most months costing £200-£250 on dates alone.
Despite financial pressures, Jaqs has no intention of leaving London. He said: "I would want to stay in London. Born in Britain, it's all you know. I grew up in London, so I don't want to leave. I think I am in a privileged position, but with all the taxes and everything being so expensive, I am just not saving."
He acknowledges that a consistent £130,000 salary could afford a comfortable lifestyle, but his income fluctuates. He said: "If someone earned £130,000 you could live comfortably. But mine's up and down. I can't feel 100 per cent comfortable. I have to work hard for that and even then it's not guaranteed."
His goal is financial freedom and ideally retiring before age 45, but he acknowledges the challenges of saving in London's high-cost environment.